American Express has officially published its comprehensive Intent Intelligence framework, marking a significant milestone as the first major card network to establish the technical specifications required for recording, authenticating, and transmitting customer instructions to autonomous AI shopping agents before any financial charge is ever processed. Released on October 13, the new framework provides vital industry plumbing for the rapidly expanding world of agentic commerce. By establishing a clear protocol for how digital assistants interact with financial infrastructure, the move directly addresses pressing questions regarding how liability will be allocated across the entire payments stack as autonomous purchasing agents become increasingly ubiquitous in everyday consumer transactions.
How the Framework Works
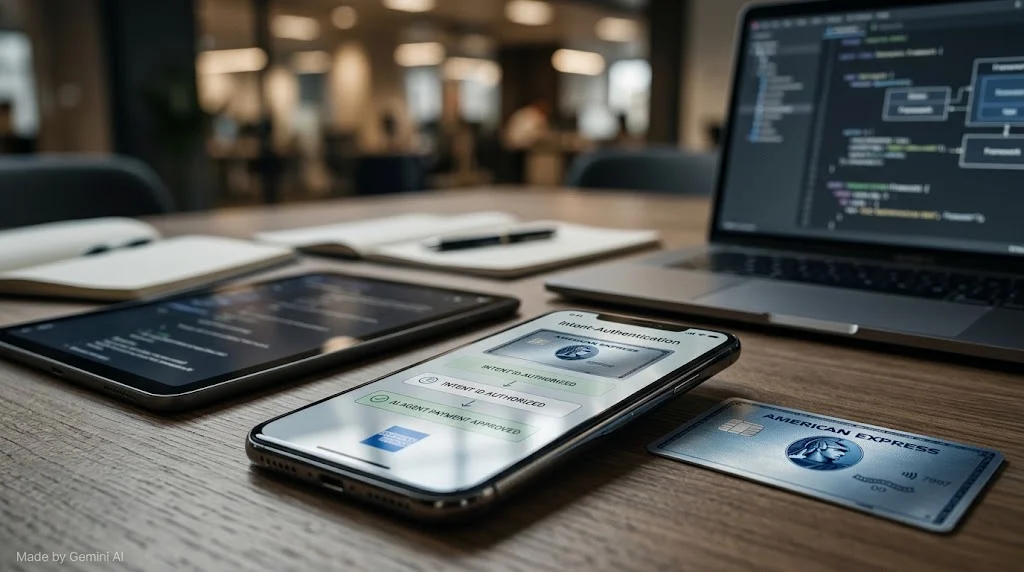
At the heart of American Express’s new architecture is the Create Intent API. This specialized interface is designed to capture a customer’s specific instructions and rigid constraints before any purchase takes place, meticulously covering parameters such as the intended merchant, a strict maximum budget, and other customized shopping preferences. Once the digital assistant records these parameters, the customer is prompted to authenticate and sign off directly on the recorded instructions.
Following this user authorization, American Express issues a unique Intent ID alongside a Proof of Intent Token. This cryptographic token encodes the high-level constraints established during the initial setup. When the AI agent proceeds to checkout, it exchanges this token for a scoped payment credential, which is used securely in place of the actual card number. Crucially, the Intent ID and its accompanying token travel seamlessly with the transaction through every subsequent phase, including standard authorization, automated fraud decisioning, and any eventual dispute resolution processes.
Hannah Bozian, the Vice President of Agentic Partnerships and Strategy at American Express, explained the core strategic rationale behind the system during an interview, noting that the objective is to pull intent much earlier into the transaction lifecycle. By shifting risk assessment to the pre-authorization stage, the system aims to catch errors before money ever leaves an account rather than attempting to untangle fraudulent or erroneous charges after they have already landed on a statement.

To illustrate how the system functions in practice, Bozian provided a straightforward scenario: a customer explicitly instructs an AI shopping agent to purchase a pair of white Nike trainers in a specific size nine. If the autonomous agent subsequently attempts to deviate from those instructions by purchasing a pair of Adidas shoes instead, the American Express network possesses the necessary visibility to block the transaction entirely at the crucial point of credential validation.
This robust framework serves as a direct extension of the foundational commitments American Express made earlier in the year. Back in April, the financial giant launched its proprietary ACE developer kit alongside Agent Purchase Protection. Under the terms of that initiative, eligible cardholders who properly authorize an AI agent and successfully pass authenticated intent back to American Express are shielded from financial charges caused by agent errors. At the time of its initial April release, that specific customer protection was framed as a forward-looking commitment with final terms still undergoing refinement, while two of the developer kit’s five core services remained actively in development.
Market Context and Regulatory Read-Across
The speed with which American Express has been able to design and deploy this technical framework is largely attributable to its unique business model. Operating simultaneously as an issuer, a payment network, and an acquirer within a closed-loop system, American Express enjoys end-to-end visibility over transaction flows. This is a level of integrated oversight that traditional four-party payment schemes cannot easily replicate without extensive coordination across multiple independent counterparties.
Recognizing the wider industry challenges posed by this multi-party dynamic, similar technical efforts are currently underway at a broader ecosystem level. EMVCo recently advanced its own draft Intent Services framework, having officially closed its public comment window on September 30. Furthermore, a coalition of six major global banks—including banking heavyweight Bank of America—published a voluntary principles paper addressing similar agentic commerce concerns.

Across all three of these major industry workstreams, the underlying direction of travel remains entirely consistent: financial liability will ultimately follow whichever entity holds an authenticated, signed record of what the customer actually authorized. This emerging reality introduces an immediate and practical operational challenge for commercial issuers and payment processors operating on traditional Visa and Mastercard rails. Any bank or processor whose proprietary agent partners fail to capture, cryptographically sign, and successfully transmit intent data through the existing authorization chain will inevitably find themselves in a significantly weaker dispute position as agentic transactions scale across global markets.
Meanwhile, the broader regulatory landscape surrounding autonomous AI commerce is still taking shape. Neither the Financial Conduct Authority nor the Payment Systems Regulator has yet issued formal, specific guidance tailored exclusively to transactions executed by autonomous AI agents. However, existing regulatory frameworks, such as the Payment Systems Regulator’s established reimbursement rules governing authorized push payment fraud, already place substantial legal and operational weight on whether a payer provided genuine, informed consent. In that specific regulatory context, an authenticated intent record of the exact type described by American Express would serve as a powerful and compelling piece of evidence.
Similarly, European regulators working diligently through the complex implementation of the third Payment Services Directive will soon be forced to confront the same fundamental definitional question: precisely at what point does an action taken by an autonomous agent legally constitute the explicit consent of the human customer?
For merchants operating online and in physical retail environments, the introduction of a payment credential scoped directly to a verified intent represents a substantially stronger dispute posture than simply accepting a traditional stored card number submitted autonomously by an automated process. Because of this enhanced security and clarity, the commercial incentives for merchants to adopt and accept intent-scoped credentials are becoming increasingly clear, meaning payment acquirers will soon need to evaluate how rapidly they can build and deploy the necessary acceptance infrastructure.