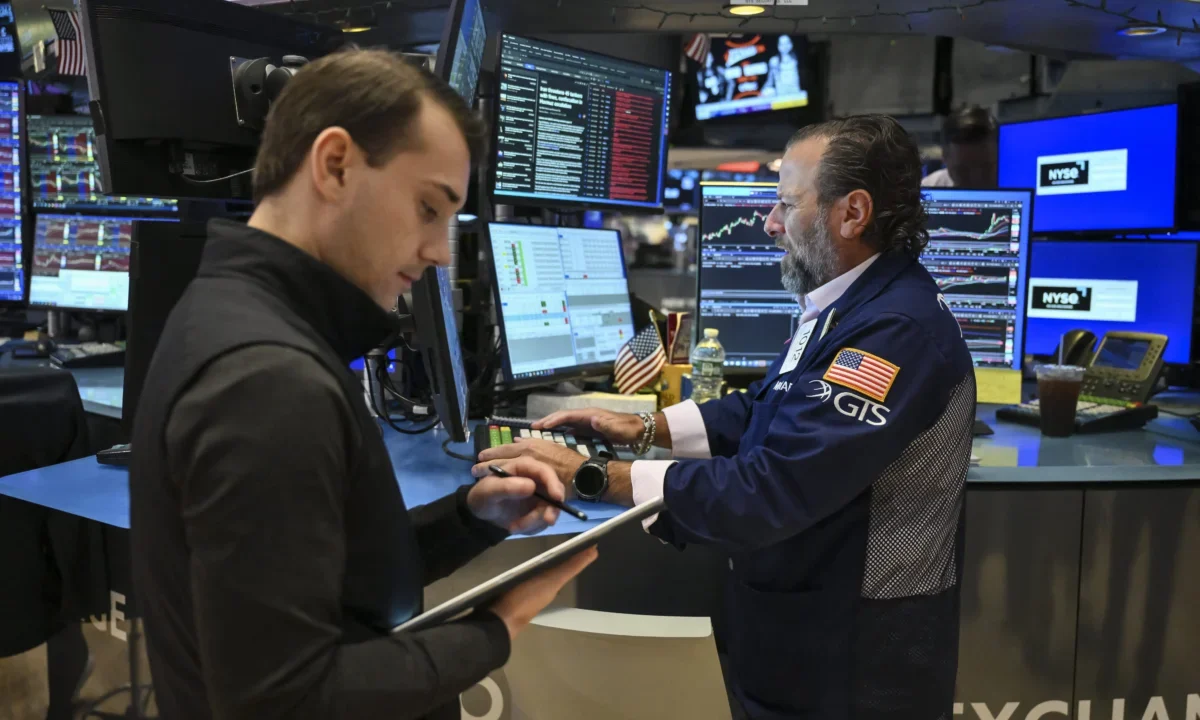
Traders on the floor of the New York Stock Exchange have witnessed an unusual market dynamic develop this year, as the frenzied momentum driving artificial intelligence stocks begins to cool and investors increasingly look toward alternative avenues for growth and stability.
A specialized version of the S&P 500 that strips out companies heavily involved in artificial intelligence briefly pulled ahead of the traditional benchmark index this year, highlighting a notable shift in investor sentiment. While tech and AI-related giants have historically powered broader market gains for years, a recent downturn in technology shares has caused the standard index to stall, allowing non-AI equities to close the performance gap significantly.
According to a proprietary index developed by Goldman Sachs, an S&P 500 variant that excludes stocks classified as "AI enablers" was up 12.4% through October 22. This performance slightly edged ahead of the standard S&P 500 index, which registered a gain of 12% over the same period. Following a late-month rebound in tech shares during Monday trading, the two indexes have moved into a neck-and-neck position, though the temporary outperformance of the ex-AI basket underscores underlying anxieties about the heavy concentration of artificial intelligence exposure in modern portfolios.
Technology and AI-related companies currently make up roughly 45% of the total weight of the S&P 500. While that massive weighting served as a formidable engine during the height of the artificial intelligence boom, it has rapidly transformed into a liability amid shifting market conditions. The S&P 500 technology sector alone has plummeted by about 7% this month, weighing heavily on the broader index, even as other segments of the market have held their ground and provided a reliable cushion for portfolios.
Investor fatigue has become increasingly apparent across both the debt and equity issues of high-profile infrastructure and software players. Market participants have begun to sour on financing vehicles associated with companies like CoreWeave and Oracle. Furthermore, equity values have absorbed sharp blows following announcements of aggressive spending strategies. Meta Platforms saw its shares sink nearly 7% on a single Thursday after management outlined plans to ramp up capital expenditures even further while issuing additional shares to fund future initiatives.
The pullback has not spared companies down the supply chain that provide the physical infrastructure, power, and equipment necessary for the massive data center buildout required by generative AI. Industrial and energy names that previously enjoyed meteoric rises—such as GE Vernova, Bloom Energy, Vistra, and Quanta Services—have all suffered steep declines during the recent market selloff, reflecting growing skepticism about the immediate return on investment for capital-intensive AI projects.
The Goldman Sachs measure, launched earlier this year in collaboration with S&P, takes the standard S&P 500 universe as its baseline, carefully filters out companies perceived to be primary enablers of artificial intelligence, and then applies the traditional S&P 500 index weighting methodology to the remaining pool of corporations.
AI Trade Loses Steam as Defensive Sectors Rally
For the vast majority of the year, the ex-AI index lagged behind the traditional S&P 500. Investors eagerly chased chipmakers, cloud-computing giants, and other businesses positioned to capture immediate revenue from the unprecedented wave of corporate AI spending. However, that performance advantage has narrowed drastically over the past several months and effectively vanished as broader market rotations took hold.
As enthusiasm for high-flying tech names wanes, investors are actively rotating capital into more defensive and stable areas of the market. Sector-specific exchange-traded funds, including the State Street Consumer Staples Select Sector SPDR ETF, the State Street Health Select SPDR ETF, and the State Street Utilities Select Sector SPDR ETF, have posted solid gains of 7% to 10% over the course of the month. The energy sector has similarly advanced by roughly 10%, though that particular movement has been heavily influenced by geopolitical tensions surrounding the ongoing conflict involving Iran.
Financial analysts are increasingly advising clients to maintain exposure to non-AI companies, both for vital portfolio diversification and as a strategic hedge against further potential pain within the technology sector. Ari Wald, a technical analyst at Oppenheimer, highlighted this shifting sentiment in an investor note, stating that the artificial intelligence pendulum has clearly swung back in favor of non-AI exposure over the preceding two weeks.
Oppenheimer has responded to the changing landscape by favoring specific industries that offer steady operational performance. The firm upgraded both commercial services and insurance to an overweight status, specifically recommending equities such as Republic Services, Cintas, Verisk Analytics, Broadridge Financial Solutions, MetLife, and Arthur J. Gallagher.
Legendary conglomerate Berkshire Hathaway is also capitalizing on the broader market rotation away from tech. Class B shares of the company have climbed 8% this month, though the holding company still trails the broader S&P 500’s total return for the year. Berkshire boasts a sprawling collection of wholly owned operating businesses, including insurance behemoth GEICO and the Burlington Northern Santa Fe railroad, alongside a massive $364 billion equity portfolio featuring blue-chip stalwarts like Apple, Coca-Cola, Alphabet, and Bank of America. Financial planners note that this deep level of operational diversification positions Berkshire well to continue outperforming if technology stocks continue to act as a drag on the S&P 500.
Other research institutions see compelling opportunities in what are described as non-tech compounders. Trivector Research has pointed to healthcare giant Eli Lilly as a prime example of enduring non-tech strength. The pharmaceutical stock has surged 22%, driven largely by the blockbuster commercial success of its weight-loss treatments. The company maintains a robust clinical pipeline, with plans to file for regulatory approval of a next-generation obesity drug with the U.S. Food and Drug Administration early in 2027.
Consumer-facing discretionary stocks outside the technology umbrella are also demonstrating remarkable durability. Viking Holdings, a prominent cruise operator, reported during its August earnings call that 40% of its river capacity and 60% of its ocean capacity were already fully booked for the 2027 travel season. Management emphasized to investors that customer demand has remained remarkably stable, noting that guests have proven resilient and continue booking future travel well in advance.
Shares of Viking Holdings have risen 15% this year, yet analysts suggest the stock retains significant room for upward movement. The average Wall Street price target stands at $109 per share, comfortably above its recent trading price of around $82. Barclays recently upgraded the cruise operator to an overweight rating with a price target of $102, pointing to the company’s compelling risk-reward profile as investors seek out reliable revenue streams outside the traditional technology ecosystem.